The Credit Line Floated Her Shelves. The Fiesta Spread Comes Out of the Same Till.
A Cagayan de Oro sari-sari store runs on platform credit that reprices overnight, while family tradition expects the same cash drawer to fund the fiesta.


She restocks her shelves without ever touching a peso. Shopee floats the inventory, GCash moves the sales, and the margin between them is supposed to be her living. The arrangement works right up until the credit line reads a different number than it did yesterday.
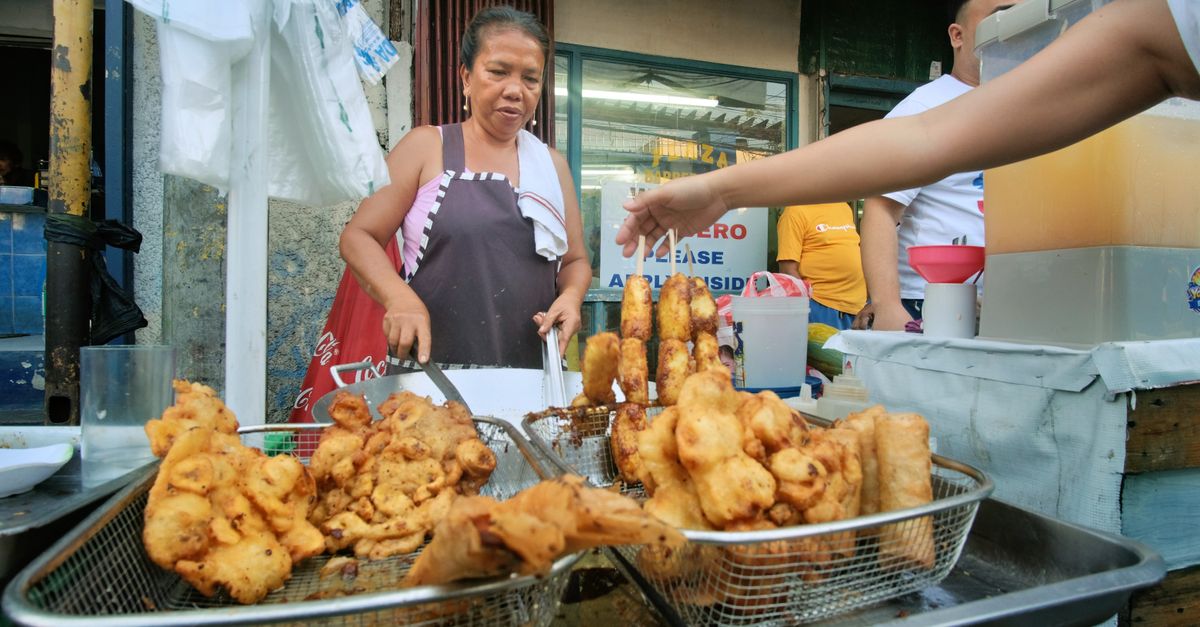
A sari-sari store in Cagayan de Oro used to run on a notebook and a trusted supplier down the road. Now it runs on an app that extends a credit limit, charges a fee to carry the balance, and quietly revises both whenever its own risk model decides to. No letter, no warning. The repayment that was comfortable last week eats the whole weekend's sales this week.
The float is only free until it isn't
Platform credit for small sellers sells itself as a lifeline. Stock now, pay after you sell, keep the lights on without a bank. The pitch leaves out the part where the terms are not fixed, and the person carrying the risk is the one with the smallest buffer.
When the fee jumps, there is no counter to argue at. The dashboard shows the new figure and expects it paid. Fintech lenders describe this as dynamic pricing. For a store owner, it means the cost of her own stock changes after she already agreed to buy it.
She cannot plan around a number that moves. A price hike on a sack of rice she can pass to customers. A reprice on her credit line she absorbs alone, because no buyer of a single sachet of shampoo wants to hear about her repayment schedule.
The till does double duty
Then fiesta season lands. The family assumes the store funds the spread, because the store is where the cash is. Lechon, drinks, the table that has to look full for the relatives who visit once a year. That money comes out of the same drawer that owes Shopee by Friday.
Saying no is not really on the table. Refusing to front the fiesta reads as the business doing well enough to be stingy, which it is not, and as a daughter forgetting where she comes from, which she has not. The obligation is older than the app and louder than the repayment alert.
So she does both. She pays for the pig, she pays the platform, and she borrows the gap from next month's margin. The float that was supposed to grow the store ends up funding a two-day feast and a repricing she never agreed to.
None of this shows up when people talk about digital inclusion lifting small vendors. The inclusion is real. So is the fee that moves overnight, the family that counts the till as shared property, and the owner left holding both. She keeps the store open on the thinnest margin either side bothers to notice, and the drawer closes each night a little further behind than the apps on her phone will admit.